
What will you walk away with?
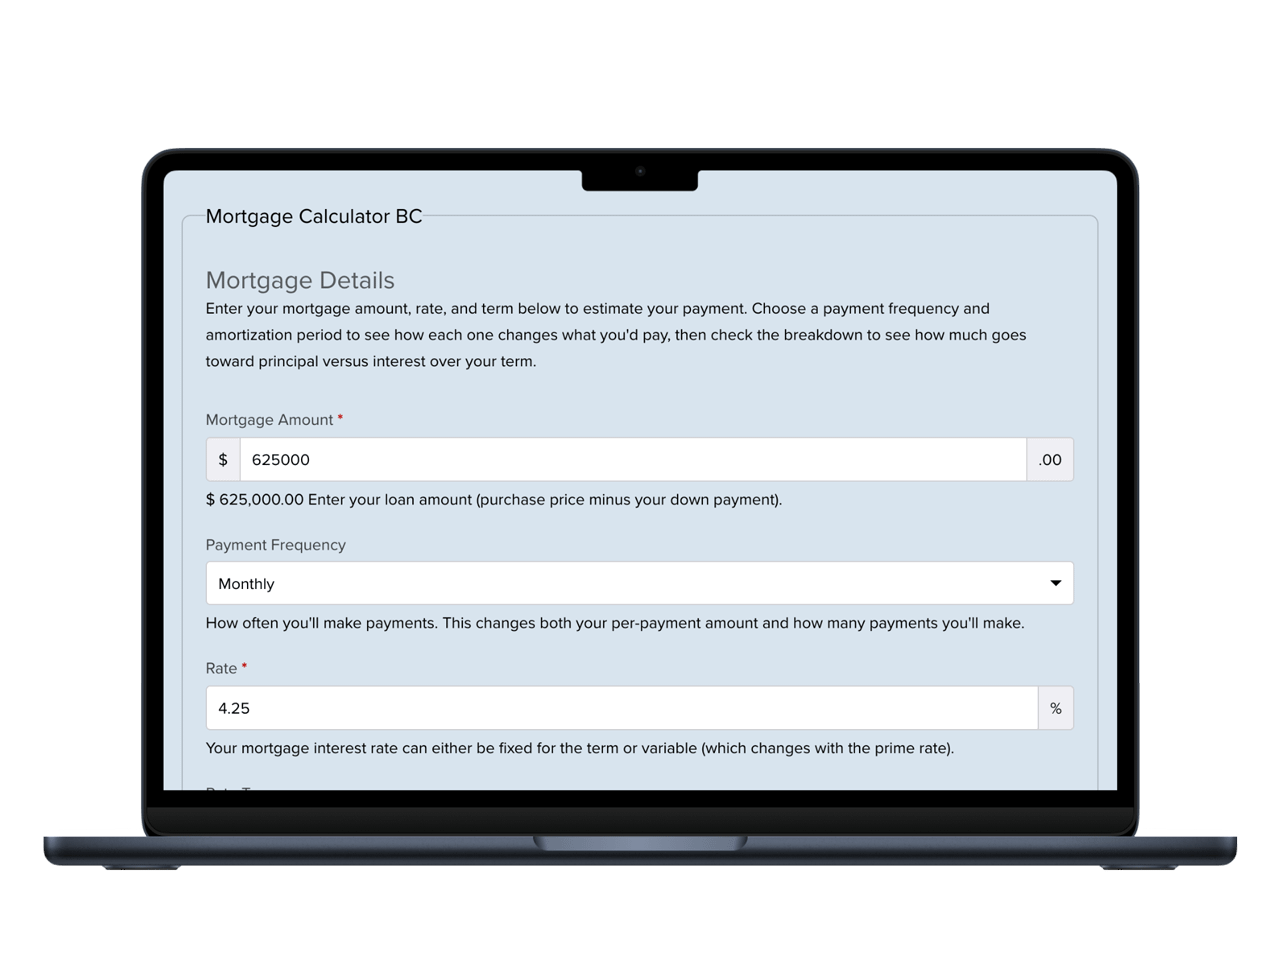
Mortgage Calculator BC
Know the real number before you offer
Why a Real Mortgage Payment Calculator Matters in BC
Every bank has a mortgage calculator, but a Mortgage Calculator BC needs to do more than spit out a rough guess. What they don’t tell you is that Canadian mortgages compound differently than the American math baked into half the online calculators, and if you’re buying in BC, your payment is only one piece of what you’ll actually need on closing day.
This calculator uses the real formula lenders here use. Below, I’ll walk through what the number means, what it leaves out, and where to go next.
Why Canadian Mortgage Math Is Different
If you’ve used a mortgage calculator built for a U.S. audience, the number you get in Canada will be slightly off. That’s not a rounding error. Under the Bank Act, Canadian lenders must compound interest on a fixed-rate mortgage semi-annually, not monthly. American mortgages compound monthly. It’s a small difference per payment, but over a 25-year amortization it adds up to real money, and it’s why a calculator that isn’t built specifically for the Canadian market will quietly hand you the wrong figure.
The calculator above uses semi-annual compounding for fixed rates, converted to whatever payment frequency you choose (monthly, bi-weekly, accelerated bi-weekly). If you’re comparing this number against another calculator and getting a different answer, check whether that tool is actually using Canadian compounding rules or just applying a generic formula.
What This Calculator Doesn't Show You
A mortgage payment estimate answers one question: can you carry the loan? It doesn’t answer what you need to get to the closing table, and in BC those two numbers aren’t close.
On top of your down payment, you’re looking at:
- Property Transfer Tax – 1% on the first $200,000, 2% on the portion up to $2 million, 3% above that, with a possible first-time buyer or newly built exemption depending on price and eligibility. Calculate your PTT here →
- GST on new construction – if you’re buying presale or new build, GST applies to the purchase price (with a rebate on lower-priced homes), and this is the single most common number buyers forget to budget for. Estimate GST here →
- Legal fees, title insurance, appraisal, and adjustments – typically $1,500–$3,000 depending on the transaction. Full closing cost breakdown →
If you want the complete picture before you make an offer, the Closing Costs Calculator rolls it all together with your mortgage numbers in one place.
BC-Specific Rules That Affect Your Payment
A few things that change your actual qualifying amount, not just your comfort level:
The stress test. Regardless of what rate your lender offers, you need to qualify at the higher of your contract rate plus 2%, or 5.25%. This determines how much you can borrow, not what you’ll actually pay, which is why your approved amount and your calculated payment above can tell two different stories.
Minimum down payment. 5% on the first $500,000, 10% on the portion between $500,000 and $1 million, and 20% on anything above $1 million or on a second property. Anything under 20% down requires CMHC (or equivalent) mortgage default insurance, which adds a premium on top of your loan and changes your amortization options – insured mortgages are capped at 25 years; uninsured can go to 30.
Amortization length. Extending from 25 to 30 years lowers your monthly payment but substantially increases the total interest paid over the life of the mortgage. Worth running both numbers through the calculator above before deciding which matters more to you: monthly cash flow or total cost.
Already Have a Mortgage? A Few More Calculators You'll Want
If you’re not shopping for a new mortgage and instead trying to figure out your existing one:
- Renewing soon? Run your current balance and remaining amortization through the calculator above at today’s rates to see where your payment lands before your lender sends you a renewal offer.
- Thinking about extra payments? Even modest lump sums or more frequent payments can cut years off a 25-year amortization. Adjust the payment frequency field above to accelerated bi-weekly and compare the total interest column.
- Paying it off early? The gap between your current amortization and an aggressive payoff schedule is usually bigger than people expect once you see it side by side.
A Note From Someone Who's Sold Through a Few Rate Cycles
I’ve been doing this since 1994, so I’ve watched rates do just about everything. The number this calculator gives you is accurate. What it can’t tell you is whether now is the right time for you specifically, whether a variable or fixed rate makes more sense based on what you’re planning to do with the property, or how your down payment source affects your options. That part’s a conversation, not a calculation. If you want to run your numbers past an actual mortgage broker before you commit to anything, take a look at our referral partners.
Related Calculators
Try our other calculators to see the full picture before you make an offer.
10 Questions You Must Ask Before Buying a Condo in BC
10 “Dream” Home Features That FAIL In Real Life
How to Buy a Presale Condo in BC and Win (2025/26 Manual)
The Best Buying Opportunity in Years? Why Vancouver Developers Are Selling Condos Below Cost
Before You Put Down a Deposit on a BC Presale, Ask These Questions
Is the Vancouver Housing Market Crash Finally Over?
Step into home ownership
Fill out our buyer intake form
Feeling unsure about buying in Vancouver’s changing market?
You’re not alone. We take the time to understand your goals, offer honest advice, and create a clear plan that makes sense for you. Let’s take the pressure off and move forward with confidence - together.
Mortgage Calculator BC
Frequently asked questions
Mortgage calculators raise the same handful of questions on every deal: why the number looks different from a U.S. site, how the stress test actually works, and what’s missing once you get to closing. Below are the ones we hear most, answered the same way we’d answer them on a call: plainly, honestly, and without the jargon.
Does this calculator use Canadian mortgage rules?
Yes. Fixed-rate mortgages in Canada compound semi-annually by law, and this calculator uses that formula rather than the monthly compounding math common in U.S.-built calculators.
What's the difference between an insured and uninsured mortgage?
An insured mortgage has less than 20% down and requires mortgage default insurance (CMHC or a private equivalent), which caps amortization at 25 years. An uninsured mortgage has 20% or more down and can be amortized up to 30 years.
Does this calculator include property transfer tax or GST?
No, this tool calculates only your mortgage payment. Use the BC Property Transfer Tax Calculator and New Home GST Calculator separately, or the Closing Costs Calculator to see everything together.
What's the mortgage stress test in BC?
You need to qualify at whichever is higher: your contract rate plus 2% or 5.25%. This affects how much you’re approved to borrow, not your actual monthly payment.
How much does extending my amortization from 25 to 30 years actually save me monthly?
It depends on your rate and loan size, but monthly savings are usually modest, while total interest paid over the full term increases considerably. Run both scenarios through the calculator above to see your specific numbers.