
Know the real number before you offer
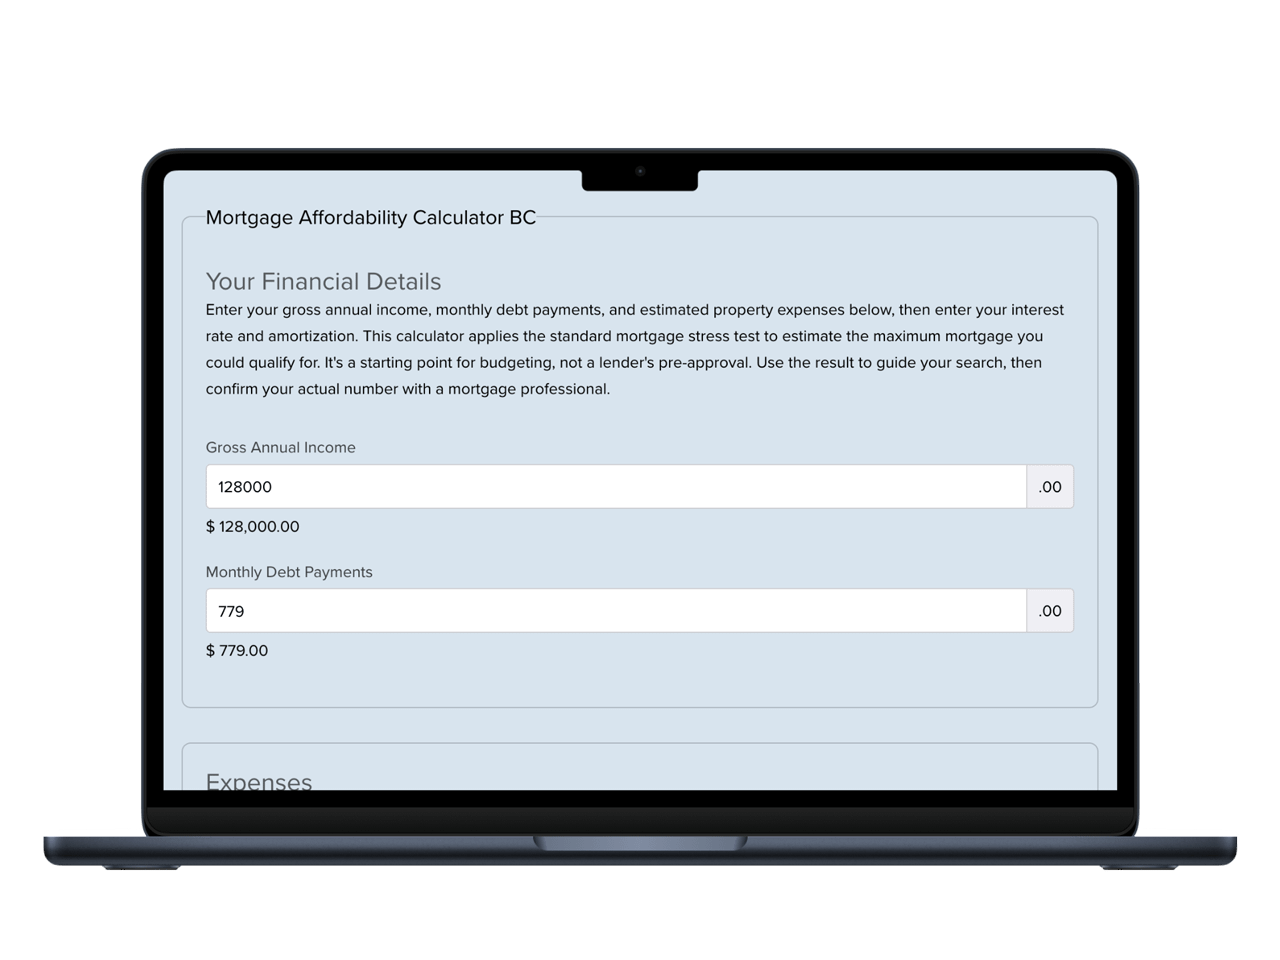
Mortgage Affordability Calculator BC
Pass the Mortgage Stress Test Before Your Offer
Figuring out what you can actually afford is a different question than what a bank will approve you for, which is exactly what a Mortgage Affordability Calculator BC is built to answer. Those two numbers are rarely the same, and the gap between them has ended more than a few house-hunting trips before they started. This calculator gives you a real number to work with, based on your income, debts, and the stress test rules lenders actually use in British Columbia today.
If this is your first purchase, our First Time Home Buyer BC: The Complete 2026 Guide covers the programs and exemptions that can change your numbers before you even get to this calculator.
How This Calculator Works
The calculator runs your numbers through the same two ratios your lender will use: GDS and TDS.
Gross Debt Service (GDS) looks at your housing costs (mortgage payment, property tax, heat, and half your condo fees if you’re buying a strata unit) as a share of your gross income. Lenders want this under 39%.
Total Debt Service (TDS) adds in everything else you owe, car payments, credit cards, student loans, lines of credit, and caps the total at 44% of gross income.
Whichever ratio you hit first sets your ceiling. If you’re carrying a lot of other debt, TDS will box you in before GDS does, no matter how much house you think your income should buy.
The calculator also applies the mortgage stress test, which requires you to qualify at the higher of your contract rate plus 2%, or the Bank of Canada’s benchmark qualifying rate. This isn’t optional, and it isn’t going away. It exists specifically to stop people from buying based on today’s rate and getting squeezed the moment they renew into a higher one.
What Goes Into the Number
A few inputs move the needle more than people expect:
- Down payment. Anything under 20% means you’re paying CMHC insurance, which gets added to your mortgage amount and increases your monthly payment. It also changes your amortization options. Our Home Buying Costs Calculator breaks down minimum down payment requirements and required income in more detail if you want to dig into that side of things.
- Amortization period. 25 years is standard for insured mortgages. Uninsured buyers (20%+ down) can stretch to 30, which lowers the payment but adds real interest cost over the life of the loan.
- Property tax and heating costs. These get baked into GDS whether you think about them or not. A pricier property tax bill in one municipality versus another can shave real dollars off your borrowing room.
Existing debt. A car loan or a chunk of credit card debt hurts your affordability more than most people assume, because it counts against you dollar for dollar in TDS, not just as a vague “risk factor.”
Why BC Numbers Look Different Than the National Average
Affordability calculators built for a national audience tend to undersell how tight things get here. Property values in Metro Vancouver and much of the Fraser Valley sit well above the national median, which means the down payment thresholds that trigger higher CMHC premiums, or push you out of insured mortgage territory altogether, kick in a lot sooner than they would in most of the country.
There’s also the Property Transfer Tax to account for, which isn’t part of your mortgage affordability math directly, but absolutely affects how much cash you need on hand to close. If you haven’t run those numbers yet, it’s worth doing before you get attached to a number this calculator gives you.
For the full picture of what you’ll need at closing beyond the mortgage itself, our Closing Costs Calculator covers legal fees, inspection costs, and everything else that shows up on your final bill.
What This Calculator Doesn't Tell You
It tells you what a lender will likely approve. It does not tell you what you should actually spend. Those are two different exercises, and conflating them is how people end up house-rich and everything-else-poor.
If your calculated maximum has you at the edge of both ratios, that’s usually a sign to look at a lower price point, not a sign to find a lender with looser standards. The math doesn’t get easier after you sign.
Related Calculators
Try our other calculators to see the full picture before you make an offer.
10 Questions You Must Ask Before Buying a Condo in BC
10 “Dream” Home Features That FAIL In Real Life
How to Buy a Presale Condo in BC and Win (2025/26 Manual)
The Best Buying Opportunity in Years? Why Vancouver Developers Are Selling Condos Below Cost
Before You Put Down a Deposit on a BC Presale, Ask These Questions
Is the Vancouver Housing Market Crash Finally Over?
Step into home ownership
Fill out our buyer intake form
Feeling unsure about buying in Vancouver’s changing market?
You’re not alone. We take the time to understand your goals, offer honest advice, and create a clear plan that makes sense for you. Let’s take the pressure off and move forward with confidence - together.
Mortgage Affordability Calculator BC
Frequently asked questions
Affordability questions tend to repeat themselves: how much you can actually borrow, what the stress test does to that number, and whether rental income helps your case. These are the ones we hear most, and we answer them the same way we would on a call: plainly and without the runaround.
How much mortgage can I afford with a $100,000 salary in Canada?
Roughly speaking, and depending on your down payment, existing debt, and current rates, a single applicant earning $100,000 with minimal other debt and a 20% down payment can typically qualify in the range of $550,000 to $650,000. Run your specific numbers through the calculator above, since property tax, condo fees, and other debt will meaningfully affect this figure.
How much mortgage can I afford with a $150,000 salary in Canada?
At this income level, with a reasonable down payment and low existing debt, you’re generally looking at a qualifying range in the $850,000 to $1,000,000 area, though this narrows fast if you’re carrying a car payment or significant credit card balances.
How much income do I need for a $500,000 mortgage in Canada?
Depending on your down payment, debt load, and current stress test rate, most buyers need a household income of about $115,000 to $135,000 to qualify for a $500,000 mortgage. Use the calculator above with your actual debt figures for an accurate answer, since this range shifts with rates. If you’re looking at new construction, check our New Home GST Rebate Calculator first, since a rebate can change how much mortgage you actually need to qualify for. Depending on your down payment, debt load, and current stress test rate, most buyers need household income somewhere in the $115,000 to $135,000 range to qualify for a $500,000 mortgage. Use the calculator above with your actual debt figures for an accurate answer, since this range shifts with rates. If you’re looking at new construction, check our New Home GST Rebate Calculator first, since a rebate can change how much mortgage you actually need to qualify for.
How much income do I need for a $400,000 mortgage in Canada?
Expect to need roughly $95,000 to $110,000 in household income, again depending on your down payment size and other monthly debt obligations.
Does rental income count toward mortgage affordability in BC?
Yes, if you’re purchasing a property with a secondary suite or a legal rental unit, lenders will typically count a portion of expected rental income (usually 50% to 80%, depending on the lender) toward your qualifying income. This can meaningfully increase what you’re approved for, which matters if you’re considering a purchase with tenant placement in mind later. This is exactly the kind of scenario Corinne Schindler at Powerhaus Mortgage Experts can walk through in detail, since rental income qualification varies by lender.
What's the difference between mortgage affordability and mortgage pre-approval?
An affordability calculator gives you an estimate based on general lending rules. A pre-approval is when a lender reviews your documents (pay stubs, tax returns, debt statements) and commits to a rate and amount for a set period, usually 90 to 120 days. Use the calculator to know what range to expect, then get pre-approved before you start seriously shopping.
Does the mortgage stress test apply to all buyers in BC?
Yes. The stress test applies to all federally regulated lenders regardless of your down payment size. Some credit unions that aren’t federally regulated have historically had more flexibility, so it’s worth asking your mortgage broker if your numbers are close to the line.
Should I rent or buy in this market?
It depends on your timeline and how the numbers actually work out, not just on headlines about the market being up or down. As a rule, buying tends to make more sense the longer you plan to stay in a home, since ownership costs are front-loaded (closing costs, mortgage interest early on) while renting costs simply repeat every month with no equity building up behind them. But your specific rent, down payment, mortgage rate, and how long you plan to stay all change the answer. Run your own numbers with our free BC Rent vs Buy Calculator to see which one comes out ahead for you over 5 years.