
What will you walk away with?
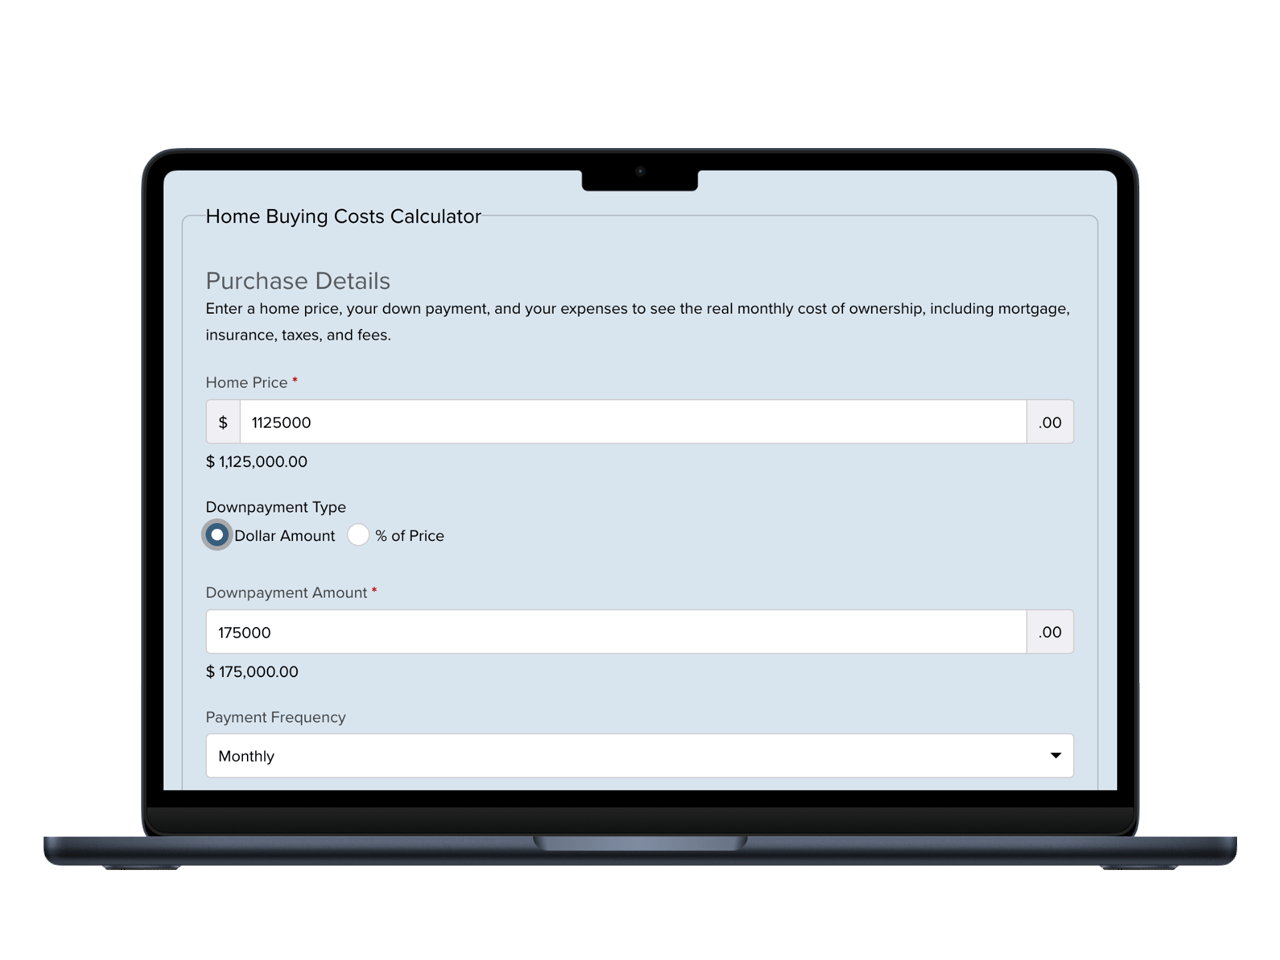
Home Buying Costs Calculator
Know the real number before you offer
The Real Monthly Number, Not Just the Mortgage Slice
Mortgage calculators usually show you one number: the mortgage payment. A real Home Buying Costs Calculator has to go further, because that number isn’t what it actually costs you to own the home.
This calculator adds in the pieces that get left out: property tax, strata fees, utilities, and, if you’re planning to rent out a suite, what that rental income actually does to your bottom line. Punch in a price and a down payment, and you’ll get the full monthly number, not just the mortgage slice of it.
What Makes This Calculator Different
Most online tools (yes, including the big lender ones) show a payment based on price, rate, and amortization. That’s a start, but it’s not what you’ll actually pay every month once you own the place. A few things this one does that most don’t:
It factors in your actual home expenses, not just the mortgage. Property tax, strata fees, utilities, and anything else recurring – you enter them once, and they get added straight into your monthly total. If you’re comparing a condo with $450/month strata against a townhouse with $150/month strata, this is where that difference actually shows up.
It handles rental income properly, not as an afterthought. If you’re buying with a rental suite or plan to rent out part of the property, enter your expected monthly rent, and it’ll net it against your total monthly cost. If the rent covers more than your carrying costs, it shows the surplus instead of a confusing negative number. This is the calculation most buyers want when weighing a mortgage helper suite: does it pay for itself, and by how much?
It calculates mortgage insurance the way CMHC actually prices it. Down payment under 20%? The premium isn’t a flat number – it’s tiered based on your loan-to-value ratio, and it changes again if you’re taking a 30-year amortization on an insured mortgage. This calculator applies both, including the extra 0.20% surcharge that comes with the 30-year option when you qualify for it as a first-time buyer or new-build purchaser. Most public calculators skip this entirely and just show you a plain 25-year number.
It uses real Canadian mortgage math. Canadian mortgages compound semi-annually by law – that’s different from the simple monthly compounding you’ll see in a lot of generic (often American-built) mortgage calculators. The payment you see here reflects the actual rate you’d be quoted by a Canadian lender, not an approximation.
You can enter your down payment either way. Dollar amount or percentage – whichever you’re thinking in. If you flip between the two, the numbers stay in sync.
What You'll Need Before You Start
- The home price you’re considering
- Your planned down payment (dollar amount or percentage, your choice)
- Whether you’re a first-time buyer or buying new construction (this affects your amortization options and mortgage insurance rules)
- Your expected interest rate and term
- Rough monthly numbers for property tax, strata (if applicable), and utilities
- If relevant, what you expect to collect in rent
You don’t need exact figures for everything. Property tax and strata are usually listed on the MLS listing; utilities can be a rough estimate based on the home’s size and age.
Understanding Your Results
Mortgage Amount – What you’re actually borrowing, including any mortgage insurance premium rolled into the loan (it isn’t paid out of pocket; it’s financed).
Monthly Mortgage – Your principal and interest payment, calculated using semi-annual compounding.
Monthly Expenses – Property tax, strata, utilities, and anything else you’ve added, totalled.
Total Monthly Cost – Mortgage plus expenses. This is the number that actually matters when you’re deciding what you can afford.
If you’re factoring in rental income, you’ll also see either your Net Monthly Cost After Rent (what you’re still paying out of pocket once rent comes in) or a Monthly Rental Surplus if the rent covers more than your total cost.
A Note on First-Time Buyers and New Construction
If you’re a first-time buyer or purchasing a newly built home, you may be eligible for a 30-year amortization on an insured mortgage – that’s only available if your down payment is under 20% and the home is priced under $1.5 million. This can also affect your Property Transfer Tax exemption, which this calculator doesn’t cover directly.
If you haven’t already, check your PTT exemption on our BC Property Transfer Tax Calculator.
Related Calculators
Try our other calculators to see the full picture before you make an offer.
10 Questions You Must Ask Before Buying a Condo in BC
10 “Dream” Home Features That FAIL In Real Life
How to Buy a Presale Condo in BC and Win (2025/26 Manual)
The Best Buying Opportunity in Years? Why Vancouver Developers Are Selling Condos Below Cost
Before You Put Down a Deposit on a BC Presale, Ask These Questions
Is the Vancouver Housing Market Crash Finally Over?
Step into home ownership
Fill out our buyer intake form
Feeling unsure about buying in Vancouver’s changing market?
You’re not alone. We take the time to understand your goals, offer honest advice, and create a clear plan that makes sense for you. Let’s take the pressure off and move forward with confidence - together.
BC Home Buying Costs Calculator
Frequently asked questions
Home-buying costs raise the same handful of questions on every deal: what’s included in the monthly number, how mortgage insurance is calculated, and whether a rental suite changes the math. Below are the ones we hear most, answered the same way we’d answer them on a call: plainly, honestly, and without the jargon.
Does this calculator include closing costs?
No, this one focuses on your ongoing monthly cost of ownership. For a one-time breakdown of legal fees, PTT, inspection, and other closing costs, use our Closing Costs Calculator.
What if I don't know my property tax or strata fees yet?
Use the listing details if you have a specific property in mind, or a rough estimate based on comparable homes. You can always come back and adjust once you have exact numbers.
How is mortgage insurance calculated?
Based on your loan-to-value ratio (how much you’re borrowing relative to the home price). If you put down less than 20%, CMHC charges a premium that increases as your down payment shrinks, and there’s an additional charge if you’re taking a 30-year amortization. This calculator applies the actual tiered structure rather than a flat estimate.
Can I use this if I'm planning to rent out part of the property?
Yes, that’s one of the main things this calculator does that most others don’t. Enter your expected monthly rental income, and it’ll show you your real net cost, or your surplus if the rent covers more than the total.
Is this accurate for a presale or new construction purchase?
The mortgage and cost math applies the same way. Just be aware that presale purchases usually involve a deposit structure over time rather than a lump-sum down payment at closing. It’s worth a conversation with your mortgage broker or Realtor about how that affects your numbers.