Enter Your Rent Scenario
Monthly rent, tenant expenses, and how much cash you have on hand today.

Know the Real Cost of Renting vs Buying
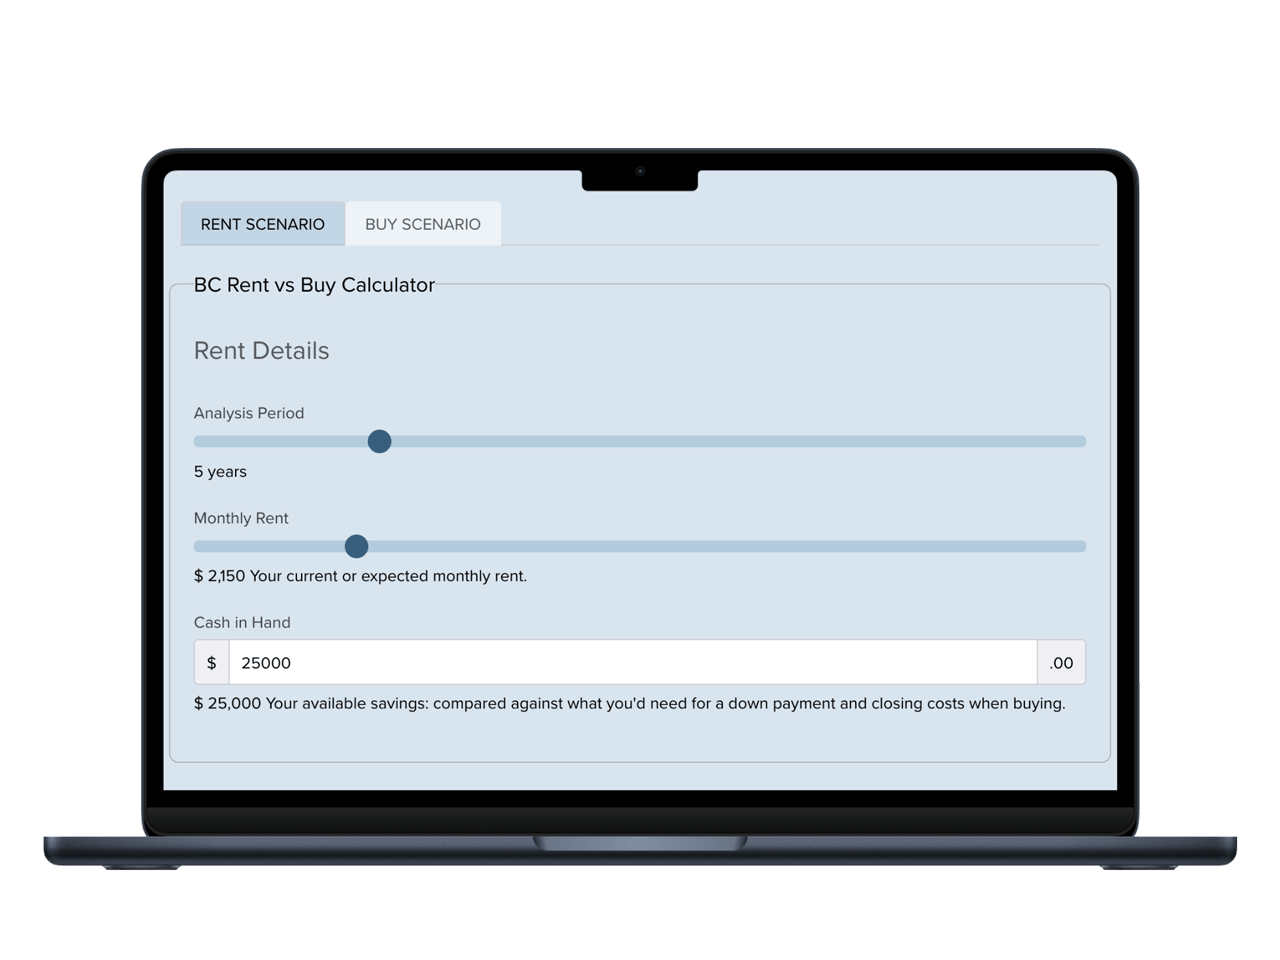
Know the real number before you decide
This BC rent vs buy calculator exists because everyone has an opinion on renting versus buying, and almost none of them have run the actual numbers for your situation.
Enter your rent, down payment, and target home, and it factors in what a generic US calculator won’t: BC Property Transfer Tax, CMHC insurance under 20% down, rental income if you’re renting out part of the property, and the semi-annual compounding Canadian mortgages require by law. Adjust the analysis period to see how the math shifts the longer you stay.
Two tabs, one comparison. The Rent Scenario tracks what you’d pay in rent and expenses over time, plus what your cash could earn if you invested it instead of putting it toward a home. The Buy Scenario tracks your mortgage, property tax, strata or maintenance costs, and the equity you’d build – minus what it actually costs to buy and eventually sell.
Both sides land on a single number: your net financial position at the end of the period you choose. Whichever number is less negative (or more positive) wins.
Monthly rent, tenant expenses, and how much cash you have on hand today.
Purchase price, down payment, mortgage rate, and whether it's a house or a strata.
How many years are you actually planning to stay - from 1 to 25?
Your net financial position for both paths, side by side, plus how much the winner saves you.
Most of the rent vs buy calculators that show up first in Google were built for American buyers, and it shows in the math:
Both are true depending on your timeline, your down payment, and what you’d actually do with the cash if you didn’t put it into a home. This tool isn’t here to tell you buying wins. It shows the crossover point for your numbers, not someone else’s average.
If you just want the shape of the tradeoff before you touch a single slider, here it is:
| Renting | Buying | |
|---|---|---|
Upfront cost | Security deposit and first month's rent | Down payment plus closing costs - often tens of thousands |
Monthly cost | Usually lower, and it's just rent | Mortgage, property tax, and maintenance - run your real payment rather than guessing |
Equity | None. Rent builds your landlord's equity, not yours | Every mortgage payment builds yours |
Flexibility | Move whenever your lease allows | Selling costs money and takes time |
Maintenance | Landlord's problem, mostly | Yours, entirely |
Tax treatment | No tax implications either way | No capital gains tax when you sell, since this assumes a principal residence. Running a home-based business is the one exception: you can deduct a portion of mortgage interest, property tax, and utilities proportional to the space you use for it |
If you’re weighing this for the first time, the First Time Home Buyer BC: Complete 2026 Guide walks through the whole process.
Try our other calculators to see the full picture before you make an offer.
Fill out our buyer intake form
Frequently asked questions
Rent vs buy questions tend to repeat themselves: how long you need to stay to make buying worth it, whether the number actually accounts for BC’s Property Transfer Tax and CMHC insurance, and whether renting really is “throwing money away.” Below are the ones we hear most, answered the same way we’d answer them on a call: plainly, honestly, and without the jargon.
It depends on your down payment, mortgage rate, and how fast Vancouver home values are appreciating in the area you’re looking at – run the numbers above with a few different analysis periods to see where the answer changes for your situation. If you’re not sure the payment itself is realistic for your budget in the first place, the Mortgage Affordability Calculator is the better starting point.
Yes, including first-time homebuyer and newly built home exemptions, where you qualify.
Yes, automatically, if your down payment is under 20%.
No, that’s a real estate cliché, not a financial fact. Whether renting or buying comes out ahead depends entirely on your specific numbers, which is the entire point of this calculator.
2.3%, down from 3.0% in 2025. It’s tied to BC’s Consumer Price Index, and the province sets it each year. Worth using as a starting point for the Annual Rent Increase field above, though your landlord can only apply it to existing tenants, not to what a new unit rents for on the open market.
That’s the actual comparison this calculator runs. Annual Investment Return is what your cash would earn if you rented instead and invested the difference. Set it to whatever return you’d genuinely expect, not a number that makes renting look better, and the calculator does the rest.
This calculator tells you what a home would cost you over time, not what income you’d need to qualify for the mortgage in the first place. For that, use the Mortgage Affordability Calculator, then come back here to see if buying actually pays off.